Table of Contents
An injury claim can fail before the facts are fully heard. Missed deadlines, gaps in medical care, or a rushed statement to an insurer can weaken your case. We’ll show you how to file a personal injury claim in Utah, protect key evidence, track your losses, and decide when legal help makes sense.
Step 1: Get Medical Care and Preserve Evidence
Your first task is to protect your health and preserve proof of what happened. Seek emergency care when needed, then follow the treatment plan your provider gives you.
Tell the doctor exactly when the injury began. Explain what happened and name every symptom, even if it seems minor. A medical record should connect the accident with your condition. Do not skip appointments without a good reason. Long gaps can give an insurer an argument that your injury was less serious.
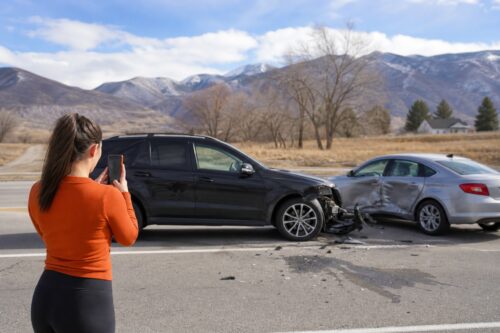
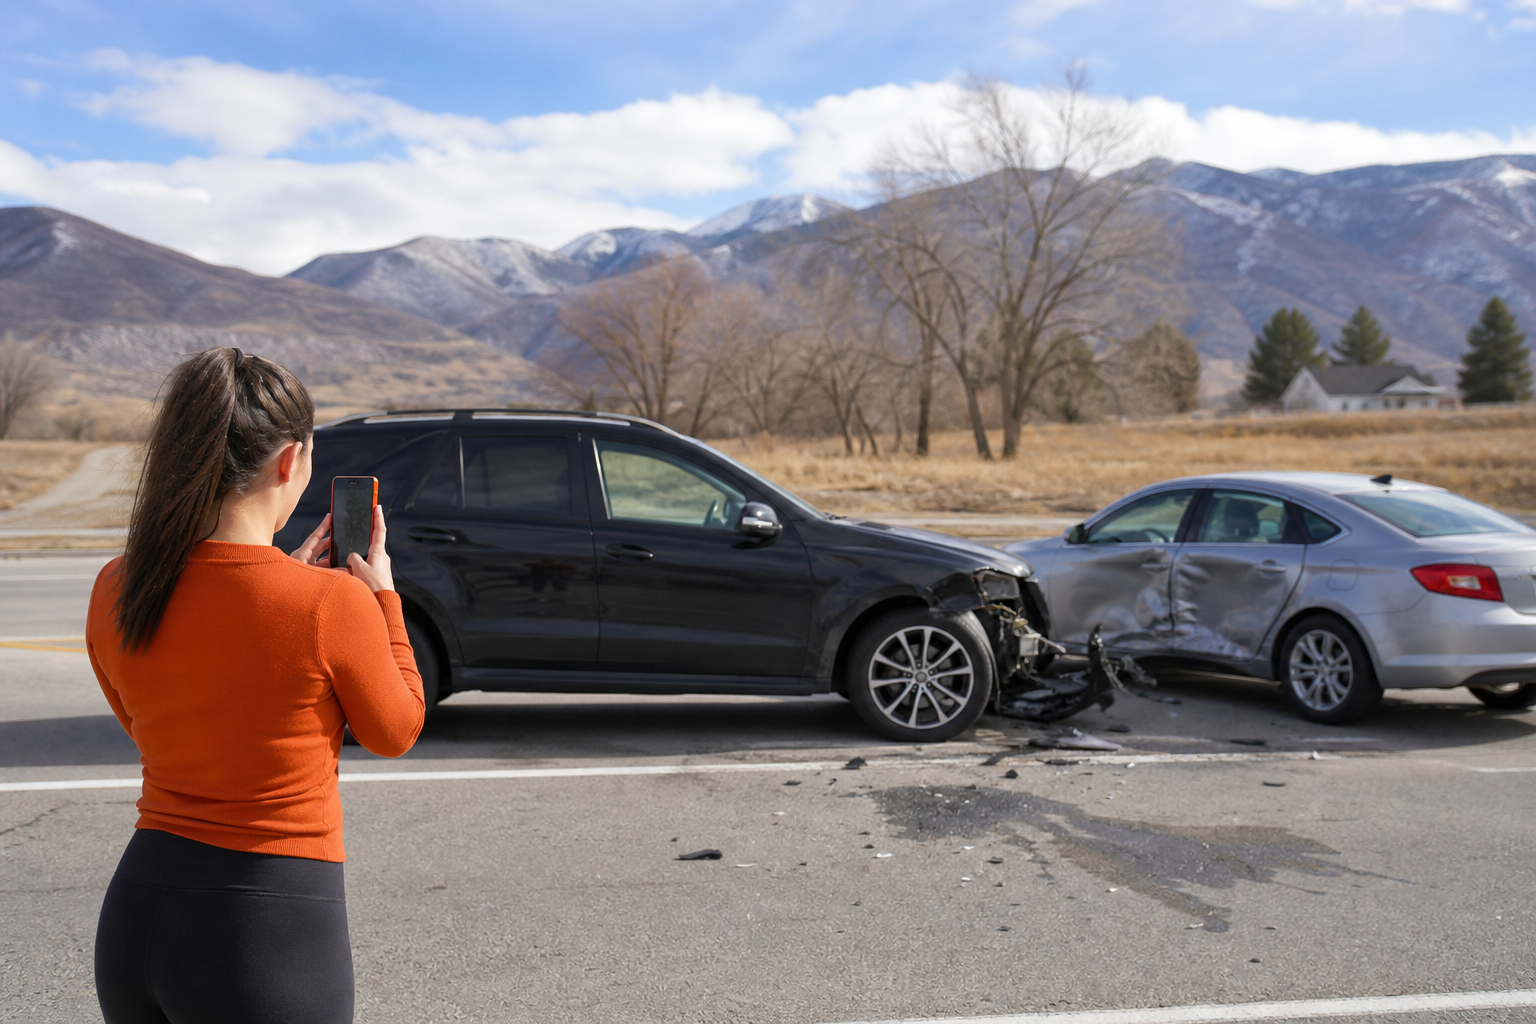
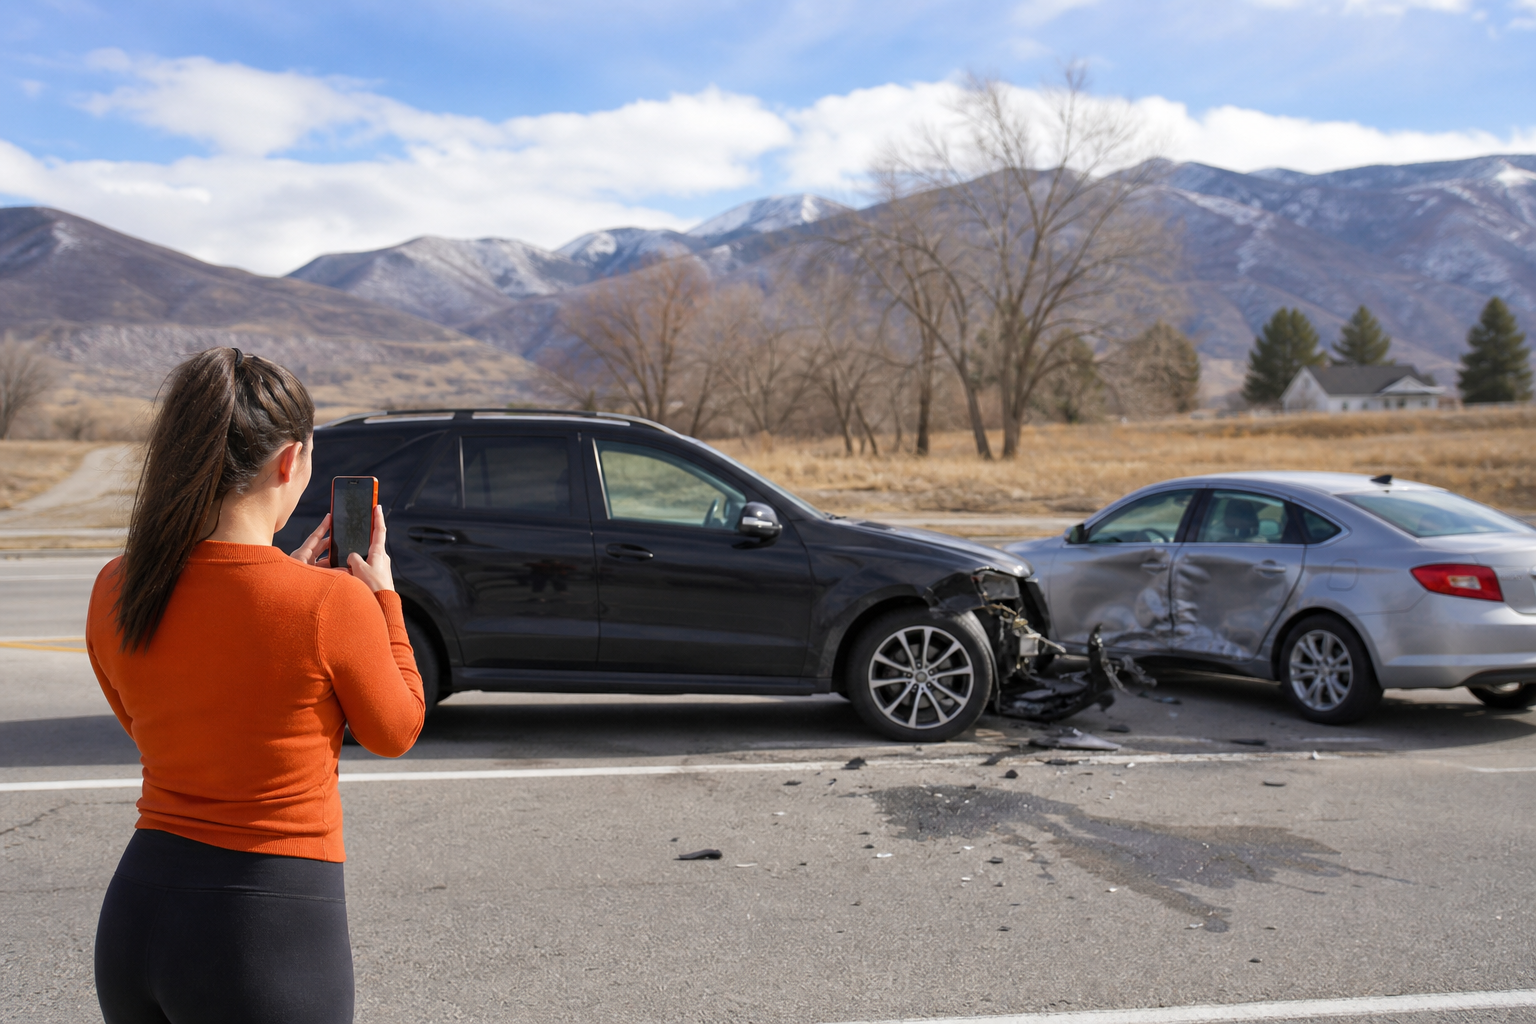
If you can do so safely, photograph the scene soon after the event. Take wide shots that show the location. Then take close shots of vehicle damage, road hazards, visible injuries, or damaged property. Save the original files. Do not edit them.
Ask for the incident number and a copy of any police or incident report. If no police report exists, gather other proof. This may include witness names, insurance details, repair estimates, security footage information, and your own written account.
Keep damaged items in their current condition when possible. Do not repair or discard a helmet, bicycle part, appliance, or other item tied to the injury before taking clear photos and asking whether it should be preserved.
You may have limited time to act, and the exact period can change with the facts. Evidence also gets harder to find as time passes. Start a case file today.
Step 2: Identify the Responsible Parties and Notify the Insurers
Before you file a personal injury claim, identify every person or company that may share legal responsibility. The answer depends on the event.
In a car crash, the other driver may be responsible. The vehicle owner, an employer, a trucking company, or another insurer may also matter. A fall may involve a property owner, a tenant, a maintenance company, or a contractor. Several parties can have separate insurance policies.
Write down each possible party and the reason you think that party may be involved. Keep this list factual. Do not accuse anyone in a social media post or public message. A careless statement can later become evidence against you.
Notify your own insurer promptly if your policy requires notice. Give basic facts about the event. You do not need to guess about fault or describe your entire medical history during the first report. Ask how to submit documents and record the claim number.
The other insurer may contact you soon. Be polite, but remember that its adjuster works for the insurance company. Avoid recorded statements until you understand what you’re being asked and why. Never sign a release before you know the full effect of the agreement.
Utah follows a modified comparative fault rule in many injury cases. In plain terms, your compensation may be reduced if you share fault, and a high level of fault may bar recovery. The exact rule depends on the claim, so do not make a final fault assessment from a quick conversation at the scene.
We understand how stressful these calls can feel. LeBaron & Jensen, P.C. can review the facts, help sort the parties, and take the stress off your plate when insurer questions become too much.
Step 3: Document Your Injuries, Expenses, and Other Damages
A strong personal injury claim shows how the event changed your life. Build that record while details remain fresh.
Keep a folder, paper or digital, with a copy of each bill and record. Add an entry whenever you receive care, miss work, or face a new expense. Useful records include:
- Medical bills, visit notes, prescriptions, and treatment plans.
- Health insurance statements that show payments or balances.
- Pay records that show missed hours or reduced income.
- Receipts for travel, equipment, home help, or other accident-related costs.
- Photos that show healing, swelling, scars, or changes over time.
Keep a short daily journal. Note your pain level, sleep, movement limits, missed activities, and the help you need. Use plain facts. “I could not drive to work because turning my neck hurt” is more useful than “I felt awful.”
Damages can include past medical costs, future care, lost income, reduced earning ability, property damage, and non-economic harm such as pain and emotional distress. You do not need to place a final dollar value on every loss today. You do need to preserve the facts that support it.
Do not hide prior injuries from your lawyer or doctor. A prior condition does not automatically defeat a claim. The legal question may involve whether the accident worsened that condition. Honest disclosure lets your legal team prepare for the insurer’s questions.
If you lack a police report, you may still have a path forward. Our guide on filing a personal injury claim without a police report explains how photos, witness accounts, medical records, and other proof can fill that gap.
Save messages and emails about the accident in one place. Keep a copy of anything you send to an insurer. A clean record helps us see what happened and keeps small details from getting lost.
Step 4: Prepare and Submit a Strong Insurance Demand
A demand letter asks the insurer to resolve the claim for a stated amount. It should be based on proof, not a number picked from the air.
Start with a short account of the event. State why the insured party was responsible and connect that conduct to your injury. Then describe your treatment and recovery in time order. Avoid dramatic language. Clear facts usually carry more weight.
Organize the supporting documents so the adjuster can check each point. A demand package may include:
- The incident or police report.
- Photographs and witness information.
- Medical records and itemized bills.
- Proof of missed work or reduced income.
- Receipts for related out-of-pocket costs.
- A statement about pain, limits, and expected care.
Wait until your medical condition is reasonably clear before demanding a final settlement. If treatment is still changing, you may not know the cost of future care. A rushed release can end the claim before later bills arrive.
Read every offer closely. Check whether it covers medical bills, lost income, property damage, and non-economic losses. Ask whether liens or health insurance claims must be paid from the settlement. A high-looking gross offer may leave less money after those obligations.
Negotiation is normal. You can reject an offer and explain why your evidence supports a different result. Keep communication calm and in writing when possible. Do not exaggerate symptoms or threaten action you do not plan to take.
LeBaron & Jensen, P.C. can help evaluate whether an offer reflects a fair settlement. We focus on the evidence, the losses, and the risks before recommending a next move.
Step 5: File a Lawsuit Before Utah’s Deadline
If negotiations do not produce a fair result, filing a lawsuit may be the next step. A lawsuit begins with a complaint filed in the proper court.
The complaint identifies the parties, states the basic facts, explains the legal claims, and asks for damages or other relief. After filing, the defendant must receive proper service. Filing the document alone does not finish the process.
Do not treat the insurance demand date as the legal deadline. A statute of limitations controls when a court action must begin. Claims involving a government entity, a minor, medical care, a death, or a different legal theory may follow different rules.
Read the current court process guidance, but do not rely on a general webpage to calculate your deadline. The clock may depend on the date of injury, the defendant, the type of claim, and facts that are easy to miss.
Once a case is filed, both sides may enter discovery. Discovery is the formal exchange of information. It can include written questions, document requests, medical authorizations, depositions, and requests to admit facts.
Answer discovery truthfully and on time. Tell your lawyer about new treatment, changed symptoms, new witnesses, or posts that mention the accident. Do not delete messages or alter records. Preservation matters after a lawsuit begins.
Many cases settle during discovery or mediation. If a case goes to trial, a judge or jury weighs the evidence. A judgment may still require collection steps, and an appeal can extend the process. Time and cost should be part of every settlement decision.
Because a missed deadline can end a claim, contact LeBaron & Jensen, P.C. early when the facts are serious or unclear. Early review gives us time to preserve proof, identify deadlines, and choose between negotiation and court.
Frequently Asked Questions About Filing a Personal Injury Claim
How long do I have to file a personal injury claim in Utah?
Filing deadlines are not universal. Government claims, medical claims, wrongful death cases, and claims involving minors may follow different rules. The date the period starts can also vary. Have a lawyer review the facts before assuming the deadline.
Do I need a lawyer to file a personal injury claim?
You can file some claims without a lawyer, but legal help is valuable when fault is disputed, injuries are serious, or an insurer asks for a recorded statement. A lawyer can assess deadlines, preserve evidence, value future losses, and handle negotiations. You remain free to decide whether representation fits your situation.
What if the insurance company denies my claim?
An insurance denial does not always end a personal injury claim. Review the stated reason and compare it with your policy, medical proof, accident evidence, and applicable law. You may respond with additional records, negotiate, pursue another coverage source, or file suit. Do not let settlement talks cause you to miss the court deadline.
Can I file a claim if I was partly at fault?
You may still recover damages if you share some fault, depending on comparative fault rules and the facts. Your award can be reduced by your share of responsibility, and a higher level of fault may prevent recovery. Avoid guessing about fault in statements to insurers. Let the evidence guide the analysis.
What damages can a personal injury claim include?
A personal injury claim may include medical costs, lost income, property damage, future care, reduced earning ability, pain, and emotional distress. The available damages depend on the injury and legal claim. Keep records of expenses and daily limits. Future losses often need medical or work evidence before they can be valued fairly.
Conclusion
Start with medical care, preserve evidence, and track the filing deadline before negotiating with an insurer. If your injuries are serious or the facts are disputed, ask LeBaron & Jensen, P.C. to review the claim early. You can get started by exploring our auto accident attorney services and gathering your records for a case review.