Table of Contents
Medical bills can grow before you know the full cost of your injuries. Early settlement demands and missing records can reduce what you keep from a Utah injury claim.
We recommend a clear order: start available benefits, track every loss, wait until your care is stable, then negotiate with full records. These steps can help protect your claim and support a fair settlement.
We reviewed 5 Utah personal injury pages currently ranking for medical bill negotiation advice. Each page was checked for five specific topics: medical liens, maximum medical improvement, narrowing a medical records release, mediation, and Utah’s comparative fault rule. All 5 pages covered the comparative fault rule, yet 2 of 5 mentioned medical liens and 1 of 5 addressed maximum medical improvement. None of the 5 pages discussed narrowing a medical records release, showing where careful documentation and timing protect a Utah settlement.
Step 1: Report the Accident and Start Available Benefits
The first step in learning how to negotiate medical bills in a personal injury lawsuit in Utah is opening the right insurance claim. Report the crash to your auto insurer and ask how to start benefits that may cover medical care.
Ask for the claim number and the adjuster’s contact details. Keep that information in one file. You should also give each hospital, clinic, and therapist both your auto insurance details and your health insurance information. Providers need clear billing instructions.
Don’t assume the at-fault driver’s insurer will pay each bill as it arrives. Billing rules can depend on the policy, the type of treatment, and the facts of the crash. Ask your lawyer which benefits may apply before you sign paperwork or make statements about fault.
Get medical care for your injuries. Tell each provider how the injury happened, but stick to facts. Follow the care plan unless a medical professional changes it. Gaps in treatment can give an insurer an argument about whether the crash caused your condition.
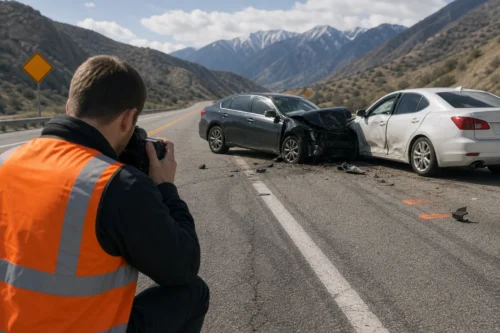
Report the accident to the proper authority as soon as you can. Preserve the crash report, photographs, witness details, damaged property records, and insurance correspondence. These records help connect the event to your bills.
We understand how stressful this feels. At LeBaron & Jensen, P.C., we help injured people sort out the first paperwork so medical billing does not take over the case.
Step 2: Document Every Bill, Receipt, Treatment, and Loss
Medical bill negotiation fails when the file is incomplete. Start one record set for treatment and costs related to the injury.
Save the full bill from each provider. Also save every Explanation of Benefits, often called an EOB. An EOB shows how an insurer processed a charge. It may show the billed amount, the allowed amount, payments, and the amount assigned to you.
Keep records for:
- Emergency care and hospital treatment
- Doctor visits, therapy, imaging, and prescriptions
- Travel costs tied to medical appointments
- Medical equipment or home changes
- Wage loss and missed work
- Paid deductibles, copays, and other out-of-pocket costs
Write down the date of each visit and the reason for it. A short treatment log can show how care progressed. Note changes in pain, sleep, movement, work, and daily tasks. Don’t exaggerate. Plain, consistent notes are more useful than dramatic language.
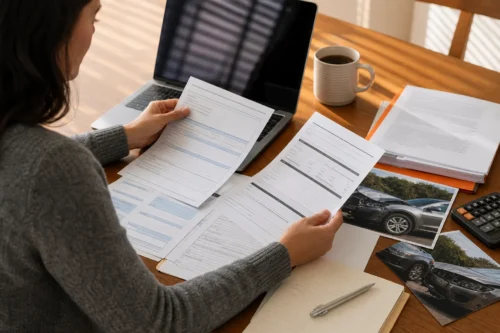
Ask providers for itemized bills. A summary balance may not show the service dates or each charge. Compare the itemized bill with the EOB. Flag duplicate charges, incorrect dates, services you did not receive, or balances that insurance already paid.
Keep proof of lost income in a separate folder. Your employer may need to confirm missed time and pay. If you are self-employed, gather records that show how the injury affected your work. Your lawyer can explain which proof fits your claim.
Medical liens need special care. A lien is a claim for payment from settlement proceeds. Review each lien and the medical lien terms in your contingency agreement. A settlement can look large until liens, case costs, and unpaid bills are deducted.
We can help you build a damages ledger that separates billed charges, insurance payments, balances, and amounts still in dispute. That gives the negotiation a clean starting point.
Step 3: Protect Your Records and Avoid Premature Settlement Offers
Insurers may make an offer before your treatment is complete. Don’t treat that offer as proof that your claim is ready to settle.
Wait until your medical picture is clear enough to estimate future care. Lawyers often describe this point as maximum medical improvement, or MMI. MMI does not always mean you feel perfect. It means your condition has stabilized enough for a medical professional to assess likely future needs.
If you settle too soon, you may lose the right to seek more money for later treatment. Most injury settlements release the claims tied to the accident. Once signed, that release can make later medical bills your responsibility.
Read every release before signing it. Watch for language covering unknown injuries, future care, unrelated conditions, or claims against more than one party. Send the document to a lawyer if the wording is unclear.
Protect your medical privacy as well. An insurer may ask for a broad medical release. A broad release can expose years of unrelated health information. We usually recommend a narrow release that limits the time period and the type of records shared.
For example, a release might focus on records related to the body part injured in the crash and a reasonable period before and after the event. The correct scope depends on the claim. Never change a release without legal advice if you don’t understand its effect.
Keep communications careful. Don’t post details about your injury or recovery on social media. Don’t give a recorded statement about medical history without first getting advice. A casual comment can be taken out of context.
Send new bills and records to your lawyer as they arrive. Waiting months can make it harder to explain why treatment changed or why a balance remains unpaid.
The decision rule is simple: don’t demand a final settlement while you still lack a reliable view of your medical costs.
Step 4: Build a Demand Package and Negotiate the Medical Bills
A demand package turns scattered records into a claim the insurer can evaluate. It should tell the story of fault, treatment, cost, and daily impact.
A strong package may include:
- A short crash summary
- Facts that support the other party’s negligence
- A timeline of medical care
- Itemized bills and EOB records
- Wage loss proof
- Photos of the crash, injuries, or property damage
- A description of how the injury changed daily life
- Medical opinions about future care when needed
Organize bills by provider and date. Then add a summary sheet. The summary should show the total billed amount, payments, outstanding balances, and disputed charges. Don’t assume the largest number on a bill is the amount you will recover.
Your lawyer may also ask providers to review balances or lien terms. Some providers may agree to reduce what they seek from settlement proceeds. That discussion must account for the provider’s rights, the settlement amount, insurance payments, and the terms of any agreement.
State a settlement demand only after reviewing the full loss. The demand should account for past medical care and reasonably supported future needs. It may also address lost income, reduced earning ability, pain, and limits on normal activities.
Expect an insurer to question causation, treatment length, billing amounts, or fault. Answer with records. If an adjuster says a charge is too high, ask which charge and why. If the insurer disputes future care, ask what medical evidence supports that position.
Don’t accept an unexplained lump-sum reduction. Request a written breakdown of the offer. Compare it with your ledger. Then account for liens, legal fees, case costs, and unpaid balances before deciding whether the net recovery is fair.
At LeBaron & Jensen, P.C., we take the stress off your plate by reviewing the records before you respond to an offer. The goal is a fair settlement that reflects your rightfully deserved compensation.
Step 5: Get Utah Legal Help and Consider Mediation if Talks Stall
Medical bill negotiations can become harder when the insurer disputes fault or blames a prior condition. A Utah personal injury lawyer can test the evidence before you make a decision.
Utah uses a modified comparative-fault approach. In general, a claimant may recover when their share of fault is no more than 50 percent, but the award can be reduced by that share. The exact rule depends on the facts and legal claims involved. A lawyer can assess how fault arguments may affect your net recovery.
Deadlines also matter. Utah injury claims can have different limitation periods based on the defendant, claim type, and other facts. Don’t wait for negotiations to end before checking the filing deadline.
When you meet with counsel, bring the crash report, claim documents, medical records, bills, EOBs, wage proof, photographs, and settlement offers. Also bring any lien notices and releases you received. A complete file lets the lawyer spot risks sooner.
We encourage readers to review our personal injury lawyer Utah resource when deciding what kind of legal help fits the claim. LeBaron & Jensen, P.C. handles personal injury matters for people dealing with accident losses and related civil issues.
Mediation may help when talks stall. A mediator is a neutral person who helps both sides discuss the strengths and risks of the case. The mediator does not decide the claim like a judge.
Bring a complete file to mediation. Include medical bills, EOBs, lien information, wage records, treatment notes, and the demand package. Your lawyer can help set a realistic settlement range and explain what happens if mediation fails.
Mediation can save time compared with full litigation, but it isn’t right for every case. The other side must participate in good faith. You also should not accept a deal simply because the session is tiring.
Legal negotiation often ends before trial, but filing a lawsuit may still be necessary. A complaint starts the civil case. Discovery then requires both sides to exchange information. Settlement talks can continue during that process, and mediation may happen later.
For a plain-language overview of mediation as a dispute process, see the definition of mediation. Comparative negligence is also explained in this reference on comparative negligence, though Utah counsel should apply Utah law to your facts.
The right time to get help is before a release is signed. We can review the bills, liens, evidence, and offer so you can make an informed choice.
Frequently Asked Questions
Can I negotiate medical bills after a car accident in Utah?
Yes, you can often ask providers or lien holders to review and reduce balances after a Utah crash. Start with itemized bills and EOBs. Compare charges with payments, then ask what amount remains due. A lawyer can help protect your settlement rights while discussing reductions.
Should I accept the insurance company’s first settlement offer?
You usually should not accept the first offer before your medical costs are clear. Early offers may arrive before future care is known. Review the offer against your full treatment record, wage loss, liens, and likely future needs. Signing a release may end the claim.
What medical records can an insurance company request?
An insurer can request records relevant to the injury claim, but you don’t have to give unlimited access to your health history. Ask for a narrow medical release that limits the time period and the type of records. Have a Utah injury lawyer review it first.
How do medical liens affect my personal injury settlement?
Medical liens can reduce the money you receive after settlement. A lien gives a provider or other payor a claim against settlement proceeds. Ask for the lien amount in writing, check its legal basis, and review how it interacts with fees and other bills before accepting an offer.
When should I hire a personal injury lawyer in Utah?
You should seek legal advice early, especially when bills are high, fault is disputed, treatment continues, or an insurer sends a release. Early review can protect records and deadlines. LeBaron & Jensen, P.C. can help assess the claim before you negotiate away important rights.
Conclusion
Don’t negotiate from a pile of unopened bills. Build a full record, wait until your medical outlook is clear, limit unnecessary disclosures, and review liens before accepting an offer. If the insurer disputes the value of your claim, send your file to LeBaron & Jensen, P.C. for a case review and a clear next step.